AA, by Alison Leslie Gold

AA, drawn for Brand Stories from Brand Champions

Alison Leslie Gold on AA. One of 121 stories from Brand Stories from Brand Champions, which I devised and curated for The Store, WPP.

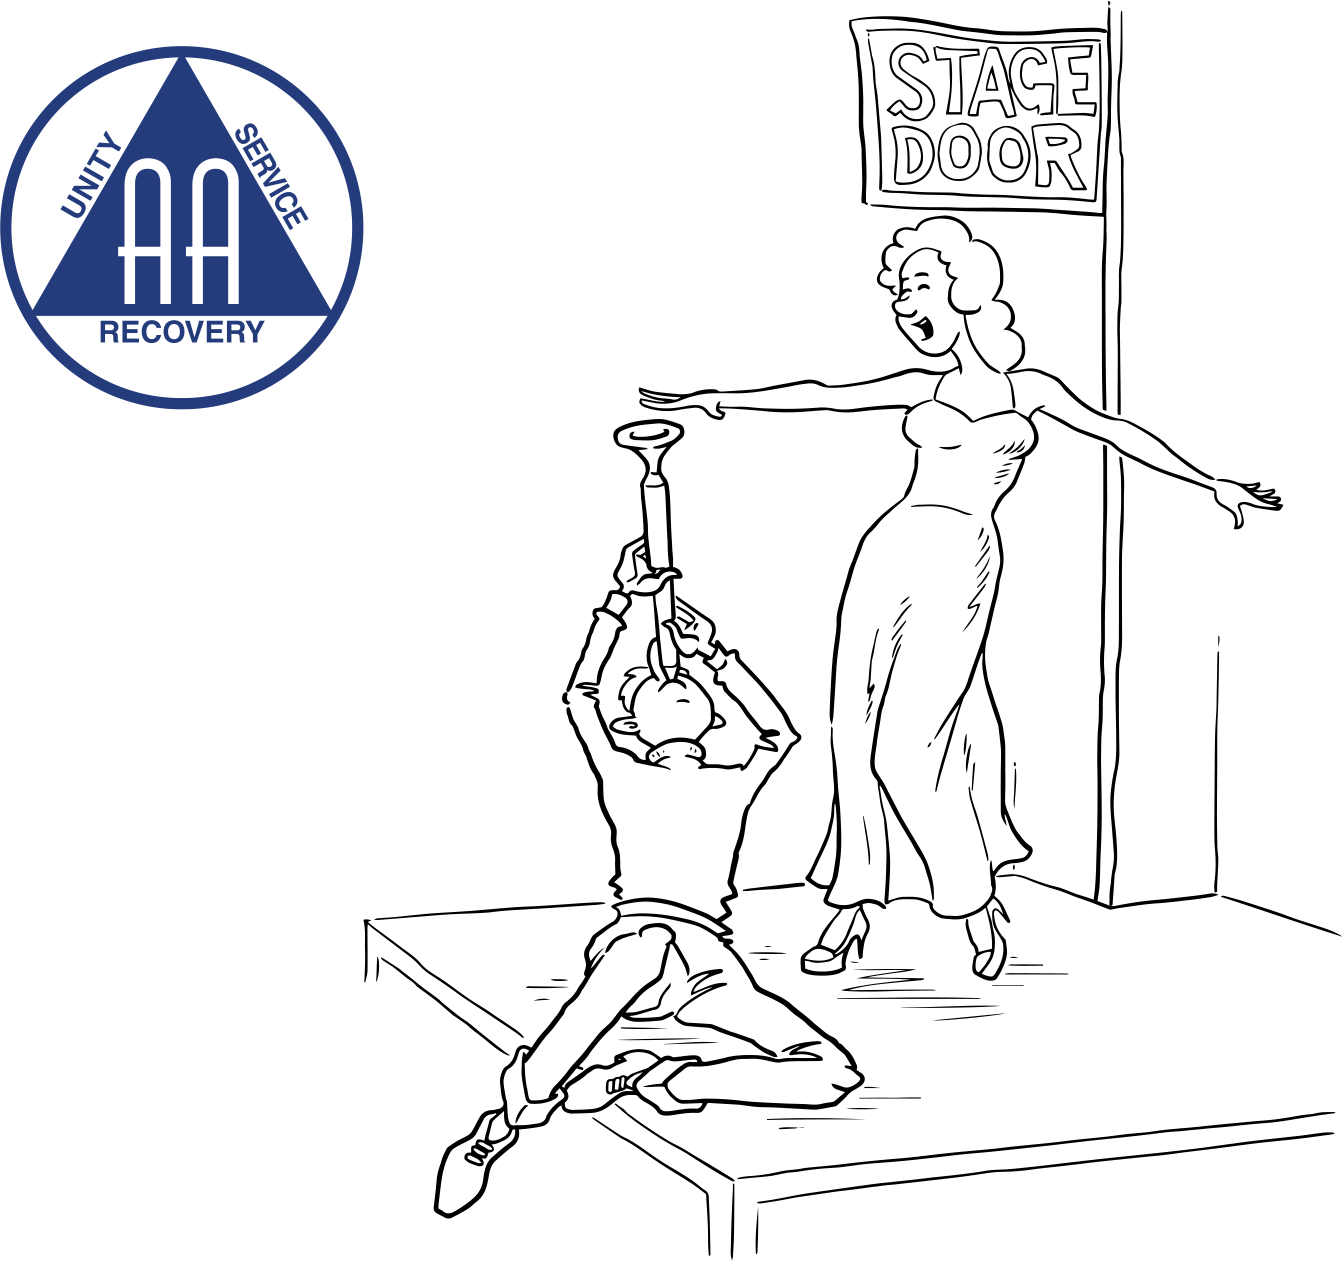
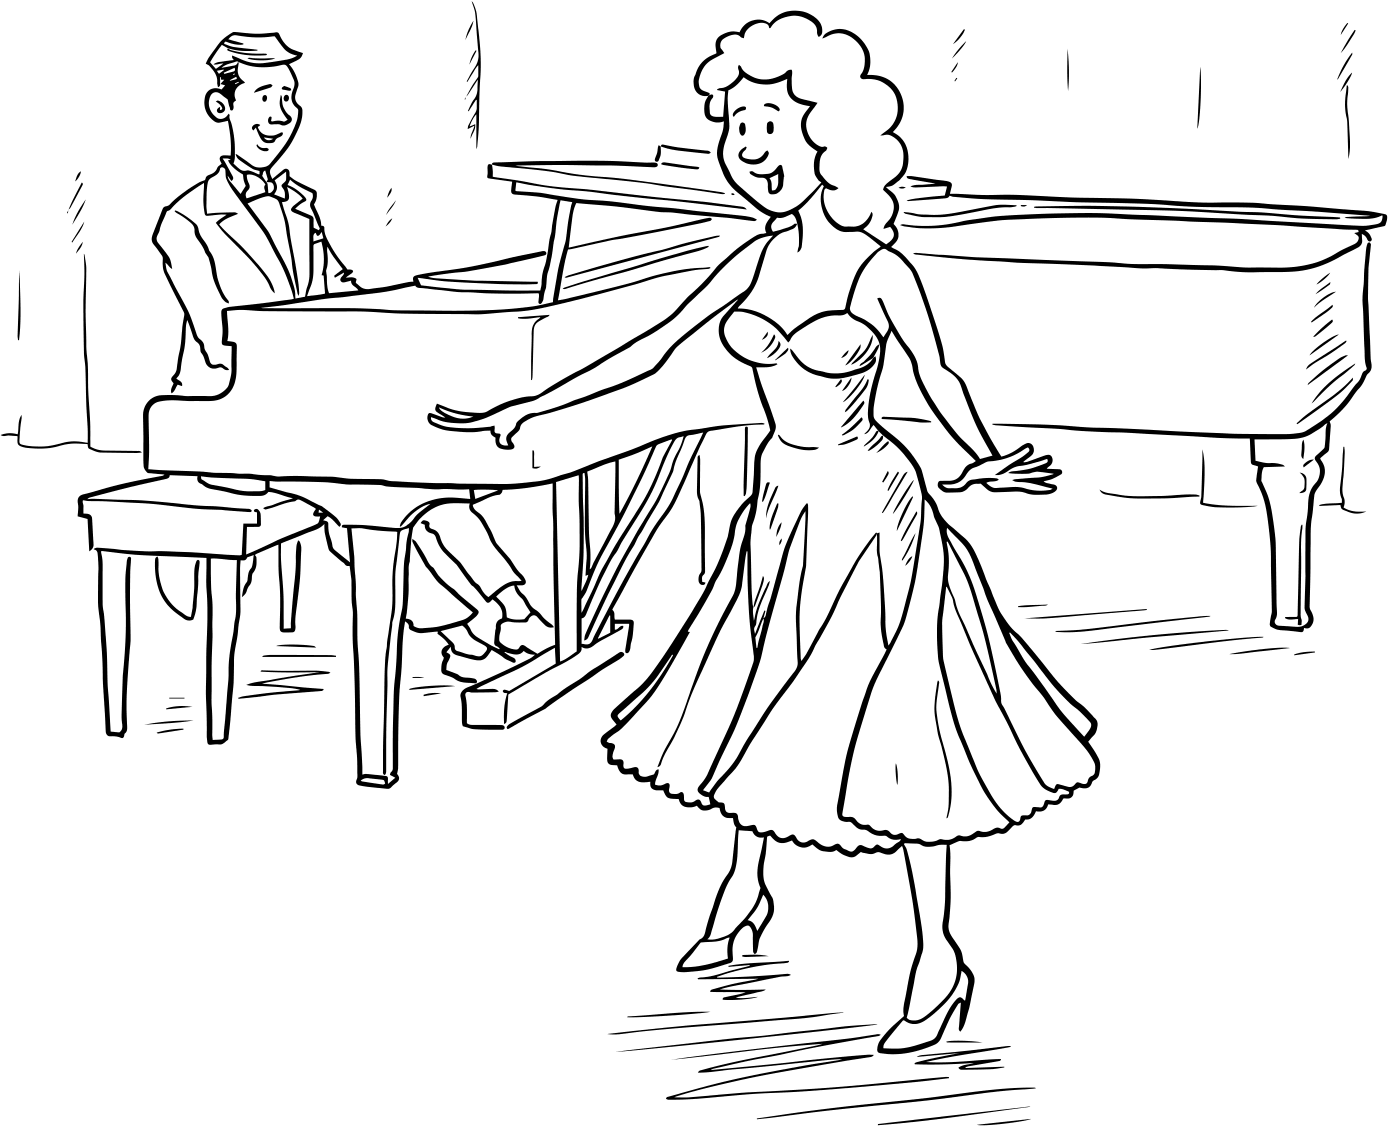
Alcoholics Anonymous at first sight: ruby-haired, sultry Susan Hayward (playing torch singer Lillian Roth) drinks too much in the 50s movie "I'll Cry Tomorrow." She drags her mink coat along the floor while wailing/ slurring "Sing, You Sinners." Helping her rise from collapse, stalwart Eddie Albert (as Burt McGuire, once also brought to his knees by whiskey), offers a steadying cup of coffee, guides her to a meeting of Alcoholics Anonymous. More meetings follow. When renewal, along with a happy, sober life results, Susan changes her tune, sings "When the Red, Red Robin …" in a clear, majestic voice:

Wake up, wake up, you sleepy head
Get up, get out of your bed
Cheer up, cheer up; the sun is red
Live, love, laugh, and be happy*

Affected by Susan/Lillian's transformation in my raw youth, the power of Alcoholics Anonymous lodged in the back of my mind though I hadn't even gulped the first of many gin and tonics, nor dragged my own coat across a dance floor. Time passed, destiny danced, quietly waiting in the wings hovered the cost-free fellowship that remains apolitical, international, multiracial, interdenominational, intergenerational. As it had for Susan/Lillian, its long open arms remained ever-ready to enfold all in need of help. Including oneself.

Begun in 1935 by a failed stockbroker and a doctor, AA has since provided sanctuary for many millions of shaky folks in more than one hundred-eighty different countries around-the-world. The organization's covenant with privacy/anonymity at a personal and public level discourages self- identification, but, as "Sing, You Sinners" warns, if one is
AA, drawn for Brand Stories from Brand Champions

…wicked and depraved
And you've all misbehaved
If you wanna be saved **

earthy Alcoholics Anonymous, its waiting empty chair, its offer of support by those who came before, the never-empty pot of coffee, is there. In the same way that a Life Saver promises a fruit- flavored circular candy, Alcoholics Anonymous (its triangular Brand logo – service, unity, recovery , enclosed within a circle), envisions a life raft upon a tumultuous river; its Brand reflects the culture, aims and overall integrity of an ego-free, self- help organization.

I've been a witness to AA's miracles, seen ruined lives salvaged, the sick get well, watched the hopeless find hope, outcasts come in from the cold. Had it not been for the modesty of anonymity, I might describe the pale-yellow silk lampshade I once wore on my head, the golden child I once neglected because another martini took precedence, the amorous inappropriateness undertaken on the S.S. Christoforo Columbo, the seizure had in a Greek island pine grove, but, I needn't. Suffice to say –

Sobriety is a jewel
That I do much adore;
And therefore keep me dancing
Though drunkards lie and snore
O mind your feet, O mind your feet
Keep dancing like a wave
And under every dancer
A dead man in his grave.***

* “Red, Red Robin” words and music by Harry Woods, 1926.
** “Sing, You Sinner” music by W. Franke Harling, lyrics by Sam Coslow, 1930
*** “A Drunken Man’s Praise of Sobriety” by William Butler Yeats, 1869 – 1939

Alison Leslie Gold

Alison Leslie Gold
Alison Leslie Gold is the author, with Miep Gies, of Anne Frank Remembered: The Story of the Woman Who Helped to Hide the Frank Family, an international bestseller that has been translated into 23 languages. Gold is also the author of Fiet’s Vase and Other Stories of Survival, Europe 1939-1945 as well as the novel The Devil’s Mistress, nominated for a National Book Award. She has recently published a new memoir titled Found and Lost: Mittens, Miep and Shovelfuls of Dirt.


There are 120 more. Brand Stories from Brand Champions collects 121 people writing about the one brand that shaped them. Amazon UK · Amazon US. The full index is at www.davidroth.com/brand-stories/stories/.
The fee was never the point. The float was.

Every guide to accepting crypto in 2026 leads with the same number: the fee. CoinRemitter at 0.23 per cent. NOWPayments from 0.5 to 1 per cent. Stripe at 1.5 per cent on stablecoins. Set against the 1.5 to 3.5 per cent that card processors charge, on UPay’s own figures, it reads like a bargain the retailer would be foolish to refuse. But the fee is the decoy. The real story is which token lands in your account, on which chain, and whether you can ever spend it.

What happened

The comparison sites have industrialised. The Bitcoin Foundation’s 2026 ranking lays out five gateways on fee, supported coins and settlement path, from CoinRemitter’s no-KYC crypto-only model to BitPay’s daily bank withdrawals in dollars, euros and sterling. UPay’s guide names eleven, adding enterprise infrastructure players like BVNK and CoinsPaid, the latter having processed over 29 billion dollars on its own reported figures, mostly for Europe’s iGaming operators.

The more interesting document is the one that ignores fees almost entirely. EdgeX’s 2026 stablecoin guide argues the choice between USDC, USDT, PYUSD and EURC “is less a question of market capitalization than of workflow fit.” USDC for regulated checkout and treasury. USDT where local liquidity decides whether a supplier can actually cash out. PYUSD inside PayPal’s walls. EURC for euro invoices. Same dollar peg on the label. Very different money in the hand.

Why it matters

Here is the shift a retailer has to grasp. A card payment is a single decision: accept Visa, or don’t. A crypto payment is a chain of them, and each link carries a cost the headline rate hides. There is the on-chain gas fee. The provider’s cut. The FX spread when you convert to the currency you pay rent in. The compliance screening. The reconciliation time. EdgeX puts it plainly: the real cost “includes the token, the chain, the provider, FX conversion, compliance review, reconciliation, and the off-ramp.” The 0.23 per cent was true and also almost meaningless.

Then there is the machine underneath. When Stripe re-entered this market it did not build rails. It bought Bridge, the stablecoin infrastructure company, and folded acceptance into the dashboard a merchant already knew. That is the tell. The value is migrating from the token to the orchestration layer, the software that mints, screens, converts and settles while the merchant sees only “paid.” Whoever owns that layer owns the margin, the data and the relationship. The coin is just the thing moving through the pipe.

And notice what crypto quietly removes. Chargebacks, estimated by Chargeback Gurus to have drained 33.8 billion dollars from merchants globally in 2025, vanish because blockchain settlement is irreversible. For the retailer that reads as a saving. For the shopper it reads as the disappearance of buyer protection. A card gives the customer a way to be wrong and get their money back. An irreversible payment does not. That is not a feature you advertise at checkout. It is a trust you spend.

What to watch

Watch MiCA do to Europe what it was built to do: sort the field. UPay’s guide already flags that EU businesses “must now consider MiCA licensing,” and CoinGate is being marketed on compliance rather than price. When regulation becomes the sales pitch, the low-fee, no-KYC operators do not win the enterprise account. They lose it.

The Roth Read. Stop shopping for the lowest fee. It is the cheapest number on the page because it is the least important one. Ask instead which token lands, on which chain, who holds it while it settles, and what your customer loses when the payment can never be reversed. The retailer who accepts crypto to save half a per cent, and hands a stranger’s software the float, the data and the buyer’s only recourse, has not cut a cost. They have sold the counter and kept the rent.

History of Retail in 101 Objects – Object 5: Market

Market · The History of Retail in 101 Objects

8000 to 2000 BC · Neolithic Shopper

In China, every neighborhood has its own little vegetable and meat market, selling local produce. These Chinese markets are a focus of activity and noise, and modern Chinese supermarkets still reflect the look and feel of these original markets with stores housing 'mini' markets and stalls within them.

In Moscow, nearly 10 per cent of all retail trade takes place in markets and indeed markets continue to occupy a special place in the hearts and minds of Russian shoppers. About half of all clothes and shoes sold in Russia are bought at markets – the prices are cheaper and sometimes the goods are newer and more plentiful than in retail outlets. Although perishable goods are also offered, grocery retailing has expanded significantly to the extent that now only about 11 per cent of all food is sold at markets.

For centuries, across every part of India, weekly Haats or 'gatherings' would see vendors gathering in market places. As towns and cities grew, small retail stores began stocking more goods, and high street bazaars were formed where traders sold a range of goods, food, and perishables.

In 1869, the Mumbai Crawford Market could be said to be the first form of shopping center in India, then in 1874, the Hogg Market was opened in Calcutta. Now known as the New Market, it was designed by an East Indian Railways Architect, R.R. Bayne, and named after the municipal commissioner of Calcutta, Sir Stuart Hogg. The Hogg Market had a garden, a red brick Gothic clock tower and benches for shoppers to rest upon.

Just a few decades ago the majority of Indian shoppers still relied on street markets. But shopping traditions here are changing too. The street markets are still appreciated for their colorful displays and merchandise, but new shopping malls offering entertainment and experiences for all the family are also attracting many customers through their doors. Retailing is now the largest private industry in India and the second largest employer after agriculture.

Since ancient times and throughout the history of man, wherever roads intersected or throngs of people gathered, buyers and sellers, or peddlers, quickly created a centralized market for the exchange of goods and services. From the original souk or bazaar to flea markets to today's sophisticated urban town centers or mega malls, the market remains the center of trade and commerce, social interaction and personal satisfaction.


Contribution to Retail History

The principle of the market is as old as civilization itself. Markets and market places are still to be found everywhere, and each country has its own traditions and customs.

See where this object sits in the sweep of retail history →


About the series. The History of Retail in 101 Objects is compiled and edited by David Roth, CEO of The Store WPP and Chairman of WPP BAV. It tells the story of retail through the objects that shaped it, from the cave to the connected store, organised across the historical periods in which each innovation made its mark. As David puts it, the history of retail is the history of mankind, and of retail’s vast contribution to society. A new object appears here every Monday.

This is the fourth edition, the World Retail Hall of Fame edition. The book, and every object published so far →

In Conversation: South African Team, University of Cape Town (UCT), South Africa

The Generation Built for AI Would Rather You Kept the Waiter

South African Team, Future Retail Challenge 2026 Winners, University of Cape Town (UCT), South Africa · recorded at the World Retail Congress, Berlin 2026.

Ask the people who will spend their whole careers alongside AI what they would build with it, and they answer by protecting the thing it could most easily replace. The human moment. That was the striking turn in this conversation with the winning student team.

They are from the University of Cape Town, one of twenty-one guests I sat down with in Berlin and, as it turned out, this year’s Future Retail Challenge winners. The brief: reimagine the store in 2030, when AI has been woven through our lives. Their case was Spur, a South African restaurant chain known for family-centred experiences.

What they did with it matters more than the win. Faced with a mandate to automate, they refused to let automation take the stage. “It was important for us to fight for the family experiences,” one of them told me, arguing that AI should step behind the human interaction rather than in front of it. On the question that keeps the older half of this Congress awake, jobs, they were clear-eyed rather than starry-eyed: AI viewed “in a very positive light,” but only if used responsibly, there “to create more time and space for humans to actually really connect in a more meaningful way.” And a warning, delivered with a calm most boardrooms lack: do not relinquish all of your responsibilities to automation.

Here is what a retailer should take from a room full of twenty-somethings. The generation you assume will automate everything is the one telling you not to. They see the shelf, the table, the greeting as the point, and the technology as the servant.

The Roth Read. If your 2030 plan uses AI to remove people, you are solving the wrong problem, and your youngest customers already know it. Automate the queue, not the welcome. Ask which human moment your technology is meant to protect, and if you cannot name one, start again.

David Roth In Conversation is a series of conversations with the leaders shaping the future of retail, recorded at the World Retail Congress, Berlin 2026 in association with the World Retail Congress. A new conversation is published every Friday.

The subsidies were never the point. The habit was.

For a year, three of China’s largest companies spent billions of dollars teaching their customers a single reflex. That reflex has now been learned. The coupons are being withdrawn, the free-delivery banners are coming down, and what is left behind is worth more than everything the subsidies cost. A new expectation. When I think of something, I buy it and get it right away.

That sentence is not mine. It belongs to Jiang Yanxin, a Beijing shopper quoted by Reuters, who ordered a doll on her way to meet friends for lunch and found a courier already at the restaurant by the time she reached her table. “I’m used to shopping this way now,” she said. That is the whole war in one line. After a year in which Meituan, Alibaba and JD.com poured money into coupons, free delivery and merchant incentives, what I call  instant retail has become the new battleground: electronics, flowers and even medicine, delivered in under sixty minutes.

The scoreboard has already moved. Goldman Sachs said in April that Meituan’s meal-delivery share had slipped from the 75 to 80 per cent it held before the price war. On Analysys data cited by Reuters, Meituan commanded 45.3 per cent of the broader instant-retail market in the second quarter, with Alibaba’s Taobao Instant Commerce ahead at 45.7 per cent and JD.com holding 7.7 per cent. The meal-delivery fight, in other words, has been swallowed whole by a bigger one.

Here is why it matters, and why the Western reader should not file this under “another Chinese price war.” The subsidies were a customer-acquisition cost disguised as generosity. Liu Xingliang, director of the Beijing-based Data Centre of China Internet, put it precisely to Reuters. The industry, he said, “has moved from the first stage of winning users through subsidies to a second stage of retaining users, expanding supply and calculating order-level economics.” Translation: the giants bought the habit at a loss, and now they must make the habit pay. The clever part was never the discount. It was recognising that a shopper who has had paracetamol at her door in under an hour will never again plan a trip to the chemist. The behaviour is a one-way door.

The damage sits where it usually sits. The food industry analyst Zhu Danpeng, quoted by Reuters, says the battle benefited consumers but the damage to small restaurant operators is still there, because a subsidised order is a thin order, and thin orders on someone else’s platform are a poor way to run a kitchen. That is the ledger the West should read most carefully. Instant retail does not create demand so much as it relocates margin, from the shop you owned to the network you rent. The convenience is real. So is the tax on it.

For a Western retailer, the lesson is not “build one-hour delivery.” It is subtler and harder. The Chinese platforms understood that logistics density, payment and media sit in one loop, so a subsidy in one part of the loop buys behaviour that monetises in another. Amazon has the pieces. Most Western grocers and chains have them scattered across four vendors and three contracts, which is why their version of instant retail is a feature nobody remembers rather than a habit nobody breaks.

What to watch. Watch retention now that the coupons are thinning. The whole thesis rests on whether the habit outlives the discount. If second-half order volumes hold as subsidies fall, the giants have bought something durable. If they sag, they have rented attention at a ruinous price, and the analysts warning that users may not stay will have their answer.

The Roth Read. Stop asking whether you can afford one-hour delivery. Ask what habit you are willing to buy at a loss, and whether you own the loop that makes it pay you back later. China just proved the subsidy is the cheap part; the expectation it leaves behind is the asset, and right now your competitor is teaching your customer to expect something you cannot yet deliver.

The sleep app learned to buy. That is the whole game now.

A sleep-tracking game now wants to do your shopping. Not point you to a shop. Do the shopping. That small, slightly absurd promise is the clearest picture yet of where retail is heading, and most retailers are not looking at it.

The app in question is a gamified sleep tracker, and the enthusiasm came from one of its users, a poster who wrote that they “absolutely love that my sleep app is now smart enough to be my own personal shopping assistant” and that “we shouldn’t have to close our game to go buy the things we need to sleep better.” The pitch, in their words: the cute AI agent can “figure out what we need, find the perfect cozy product, and buy it for us right inside the app.” The industry has a drier name for it. Agentic commerce. The user preferred “magic.”

Strip away the glowing shopping bags and the mechanism is stark. The app has your data, the app has your attention, and now the app proposes to have your wallet. Meta is building the same shape at the other end of the scale, with Muse, pitched as a personal AI agent to “get more done” across everyday tasks. A sleep game and a trillion-dollar platform are converging on one idea: the software that sits closest to you should also be the thing that buys for you.

Here is why it matters, and it is not the novelty. For thirty years the contest in retail was for the shelf, then for the search result, then for the feed. Each was a fight to be seen by a human who would then decide. The agent removes the human from the middle of that sentence. The sleep app does not show its user a page of pillows and mist diffusers to browse. It picks one. The moment of truth, the instant an impression becomes a purchase, moves from a shopper’s eye to a model’s judgement. And the model was trained, tuned and paid for by whoever owns the app.

Follow the incentives, because they are the story. When an agent buys “the perfect cozy product,” who defined perfect? The brand that optimised its product page for machine reading, as sellers on the ecommerce forums are already asking how to do. The brand that struck a commercial deal with the platform. The platform’s own private label. Perfect is a slot, and slots get sold. The retailer’s old question was how to rank on the shelf. The new question is what the agent believes about you, and what it costs to change that belief.

There is a harder edge underneath the cosiness, and it deserves naming. To buy for you, an agent needs your payment details, your address and standing permission to spend. One engineer, writing about giving an AI agent shell access, put it plainly: the agent “has everything you have because it is you” as far as the system is concerned. A sleep app that can charge your card while you sleep is a convenience and a surface for things to go wrong, in exactly equal measure. The trust you extend is not to a brand you chose. It is to an intermediary that chose for you.

China worked this out first, as it usually does. Alibaba and JD.com spent a decade collapsing discovery, payment and delivery into a single tap inside a super-app, so the distance between wanting something and owning it shrank to nothing. The West is now arriving at the same destination by a different road, through the AI agent rather than the super-app. The lesson is identical. Whoever owns the last decision owns the margin.

What to watch. Watch for the first agent that buys against its user’s stated wish, quietly steered by a commercial arrangement the user never saw. That is the moment the debate stops being about magic and starts being about disclosure, and it is coming sooner than the glowing shopping bags suggest.

The Roth Read. If you run a brand, stop optimising the page a person reads and start optimising the answer a machine gives. Your next buyer does not have eyes, a budget it can be tempted past, or a reason to remember you fondly. It has permissions, a checkout, and whatever the platform told it about you last.

America shut the door on the robot. Berlin propped it open. Now Europe has to choose.

The most interesting thing at IFA Berlin this week is not a robot. It is a legal document, three thousand miles away, that decided which robots you will be allowed to buy.

On the show floor at Messe Berlin, Chinese humanoid makers arrived in force. MagicLab, a Suzhou company founded in January 2024, opened its first major European trade show with the MagicBot X1, a 31-degree-of-freedom humanoid standing 180cm tall, and reports on its own unaudited figures more than 12,000 units shipped and an order book above RMB 1.1 billion, roughly £120 million. Galbot ran a fully autonomous store from Booth 160. Zeroth showed off the W1, a tracked home robot that carries 110 pounds. All real, all working, all drawing the longest stares in Hall 25.

And all, as of five weeks ago, barred from the United States. On 28 July the US Federal Communications Commission added foreign-produced robots to its Covered List, classifying any mobile robot over 4.4 pounds that senses, connects and navigates as posing, in the FCC’s words, “an unacceptable risk to US national security.” The definition, as K&L Gates set out on 3 August, catches nearly every machine on that Berlin runway. Washington shut the door. The TechTimes coverage notes more than 930 Chinese companies have pivoted toward Europe in the wake of it.

So here is the thing worth saying plainly. America did not make a technology decision. It made a data decision. The robots are excellent. The question the FCC asked was not “can it fetch the item from the shelf” but “where does what it sees go next.” A humanoid working a pharmacy shift or patrolling a home is a sensor package on legs: cameras, microphones, a floorplan of your store, a map of your customers’ movements, a feed uploaded to a cloud. And China’s National Intelligence Law obliges Chinese firms to assist state intelligence work when asked. That obligation travels with the device, GDPR or no GDPR.

This is the retail read, and it is uncomfortable. The store estate is about to fill with autonomous machines, and the best ones, on price and capability, are Chinese. A retailer weighing a fleet of shelf-scanners or greeters is no longer just buying labour. It is buying a data posture. Every aisle those robots walk becomes a question about who else, ultimately, can see it. That is a boardroom conversation, not a procurement one, and most boards have not had it.

The China lesson here is not the scare. It is the speed. Washington’s ban did not slow these firms; it rerouted them, and within weeks they were on a Berlin catwalk. That is the structural advantage the West keeps underrating: manufacturing scale and iteration velocity that turn a closed market into a redirected one overnight. While Brussels debates a framework, Suzhou books a booth. One vendor, AiMOGA, has already cleared the EU’s EN 18031 standard, certified by TÜV Rheinland. The compliant path exists. Most exhibitors simply have not walked it yet.

Which leaves Europe with the decision America has taken off its own table. Copy the ban and lose access to the best hardware on the market. Wave everyone through and inherit the exposure. Or do the harder thing: build the standard, insist on it, and buy on proof rather than fear.

What to watch. Watch certification, not spectacle. The number that matters over the next year is not units shipped or backflips performed. It is how many of these machines carry an independently verified European compliance credential. That badge, dull as it sounds, is about to become the most valuable thing a robot can wear onto a Western shop floor.

The Roth Read. If you are putting robots in your stores, stop asking what they can do and start asking where what they see goes. Insist on a data layer of your own or an independent one that does not leave your jurisdiction. The demo will dazzle you; the data flow is the deal. Buy the robot that can prove its answer, not the one that gives the best show, because your customers will not forgive you for the map you handed away.

History of Retail in 101 Objects – Object 4: Cuneiform Tablet

Cuneiform Tablet · The History of Retail in 101 Objects

8000 to 2000 BC · Neolithic Shopper

Civilization's need to write things down, make a list, keep a record, categorize data and thereby pay taxes, goes back to the earliest times. The first system of writing used to record this information (that is known to us) is called 'Cuneiform script'.

Cuneiform used pictorial symbols set out in columns on clay tablets, using a blunt reed for a stylus. The blunt reeds left a 'wedge shaped' impression, and this is where the name cuneiform comes from, the Latin for 'wedge'.

This writing system began in Sumer, in Mesopotamia, as long ago as 3300 BC. The early tablets were in their simplest form principally used for record keeping – agrarian inventories for grain, animals and equipment.

But as the ancient world increasingly urbanized, these writings took on a more commercial form and were employed to record bargains sealed, ships' cargoes, and lists of manufactured goods.

Early Sumerians used cuneiform to list the clay tokens they used to exchange and store their agricultural and manufactured goods. The clay tokens were put in clay containers and then impressed onto the sealed containers, one picture for each token inside the container. As time passed, it became a standard practice for the major cities to date documents by year, names, and their respective kings. It also became a way of calculating how much people should pay in taxes.

These early writings in turn led to their use for everyday purposes, not least in shopping. Dr Irvine Finkel, of the British Museum and noted Cuneiform scholar, has established that some of the earliest tablets he has examined are shopping lists!


Contribution to Retail History

Cuneiform tablets highlight our shopping journey from the ancient world to modern times. The shopping bag and the shopping list have survived the journey of time and civilizations. Both have been in use for millennia and whilst we have little evidence of an ancient bag, it is interesting to see from the many clay tablets that have survived, that the ancients wrote out their lists just as we do today.

See where this object sits in the sweep of retail history →


About the series. The History of Retail in 101 Objects is compiled and edited by David Roth, CEO of The Store WPP and Chairman of WPP BAV. It tells the story of retail through the objects that shaped it, from the cave to the connected store, organised across the historical periods in which each innovation made its mark. As David puts it, the history of retail is the history of mankind, and of retail’s vast contribution to society. A new object appears here every Monday.

This is the fourth edition, the World Retail Hall of Fame edition. The book, and every object published so far →

In Conversation: Jaume Miquel Naudí, Tendam

The consumer wants to pay less. That is mathematics, not strategy.

Jaume Miquel Naudí, Chairman & CEO, Tendam · recorded at the World Retail Congress, Berlin 2026.

Ask a retail chief executive what all their fragmented, unpredictable, endlessly-segmented consumers still have in common, and most will reach for a trend. Jaume Miquel Naudí reaches for arithmetic. “They want to pay less. That’s mathematics.” You can do whatever you want, he says, but the number bends one way.

Miquel is Chairman and CEO of Tendam, the Spanish fashion group whose loyalty clubs count more than 27 million members. That last figure is not a footnote. It is the whole thesis.

He frames the next few years as a film with all the spicy elements: fear, tension over pricing, the eruption of AI, and consumers seeking truth. But the discipline underneath the drama is where the value sits. Loyalty clubs are 75 per cent of Tendam’s business, so that is where the money goes. Not cost savings, which he will take but does not prize. Investment in what makes the business different: consumer behaviour, personalisation, pricing. On technology he refuses the single big bet, running instead a pyramid: infrastructure at the base, some 25 quick wins in the middle to keep the organisation excited, and the strategic projects on CRM, demand forecasting and margin optimisation whose payback comes later. “Momentum is important,” he says, and he means it as an operating principle, not a mood.

Then the human turn. Push everything to pure science, he warns, and you land in a world of one product, one car, one microchip. The job is to serve the dream as well as the infrastructure.

For any brand owner, the lesson is uncomfortable and clarifying. Know your one consumer, forget the rest, and earn the right to charge for the dream by first being true.

The Roth Read. If your customer wants to pay less and buy less, price is not your problem to solve, it is the condition you build inside. Decide today which one difference justifies your margin. If you cannot name it, your shopper already has: it is the price.

David Roth In Conversation is a series of conversations with the leaders shaping the future of retail, recorded at the World Retail Congress, Berlin 2026 in association with the World Retail Congress. A new conversation is published every Friday.